
Boston condos for sale: What’s the deal with mortgage rates?
Boston Condos for Sale and Apartments for Rent
Boston condos for sale: What’s the deal with mortgage rates?
October 5,2026: Mortgage rates are higher than they were on Friday and over 7.00%. Today’s national average on a 30-year fixed-rate mortgage is 7.49%, according to Bankrate. If you choose a 15-year fixed-rate mortgage, the average rate is 6.78%.
The bond market selloff has been putting upward pressure on mortgage rates, which experienced their largest weekly jump in four years last week, according to Freddie Mac. The weekly survey revealed rates have increased more than a full percentage point over the course of this year, and they’re now at their highest level since November 202
You may have seen the Boston headlines saying mortgage rates have climbed to the highest point since January 2025. And if that’s left you reluctant to buy a Boston condo for sale, here’s what you need to remember…
That’s not necessarily the number you’d get.
It’s a common misconception that the rate you see in the headlines is the same one you’d get when you buy. The truth is, mortgage rates shift often, and the rate you actually end up with can vary a lot from what you may see or hear about.
What Determines Your Real Rate?
Advertised rates and “real rates” aren’t always the same. That’s because real rates are based on your specific situation, which includes your overall finances and goals. The rates you see in the headlines can’t possibly reflect that.
That’s why only a lender can tell you what your real rate will be. To figure out your unique number, they’ll look at:
Your credit score: Your credit score includes your payment history (if you’ve made late payments – and how often), credit utilization (are your accounts maxed out, or do you have available credit?), and the length of your credit history (how long have your accounts been open?). For example, someone with an exceptional credit score may qualify for a better rate.
Your debt-to-income ratio (DTI): This is calculated by dividing your monthly debt payments by your monthly income before taxes to come up with a percentage. The higher your DTI, the higher your rate could be.
The down payment size and Loan-to-Value (LTV): Your down payment is the percentage of the home’s price you will put down. The LTV is the percentage of a home’s sales price that equals your mortgage.
The type and term of loan program options: Your loan officer will walk you through different loan options based on what you qualify for. Mortgage rates can vary between different loan products and programs.
Even after you find a Boston condo you love, other things can have an impact too. For example:
A mortgage rate buydown: This helps you get a lower mortgage rate, and by extension, a lower monthly payment, by paying an upfront cost. Sometimes a seller, builder, or another party may even offer to cover that cost themselves as an incentive for you to buy.
Seller concessions: Sellers are allowed to pay buyer closing costs according to most loan program guidelines. Seller-paid closing costs can add up to thousands of dollars, which can free up some cash for you to increase your down payment, pay down debt, or make other financial adjustments to try to get a better rate.
There’s a lot that can ultimately have an impact on your actual rate.
Your First Step? Getting Pre-Approved.
If you want to know if your number could be higher or lower than the headlines on social, you need to talk to an expert. A simple conversation with a loan officer can help you determine when you’ll be ready to buy, how much you can borrow, and of course, what your real rate will be.
Your lender may recommend a pre-qualification and pre-approval:
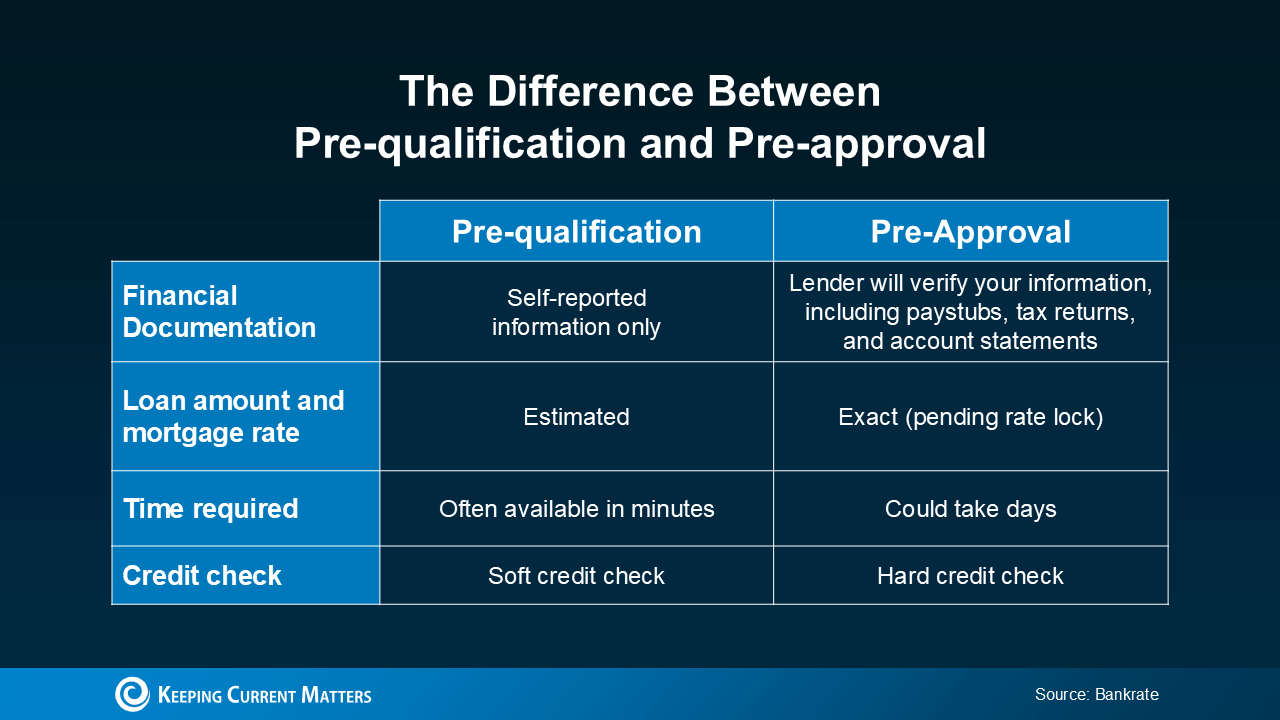
Pre-qualification is a general estimate of what you might be able to borrow based on self-reported information.
On the flip side, pre-approval is actually a conditional commitment from a lender based on verified information.
Just know that, of the two, the pre-approval process gives you a more accurate picture of your options than pre-qualification. Bankrate gives a quick comparison so you can see why:
How To Get Ready for the Conversation
Ask your lender what documents you’ll need to gather for that conversation. And keep these questions in your pocket too. They’re good things to go over when you talk:
What will I gain or lose by waiting to buy a home for 3, 6, or 12 months?
Will I get any tax advantages by buying a home – and what are they?
What’s the benefit of buying a home and starting to build equity now versus waiting? And how does that impact my finances in the long run?
How will rate changes in either direction affect me?
Once you find out your rate, maybe you can buy now. Or maybe you still need to wait. But at least you’d know your options and can make an informed decision.
Boston Condos and the Bottom Line
Headlines and social media make today’s rates sound high. But you have to remember, the rate you’re seeing online and your actual rate could be different. The only way to know what your rate could be is to talk to a trusted lender.
With the right help, you can find out what your real rate is – and where it can take you.
Boston condos for sale: What’s the deal with mortgage rates?
- 30-year fixed: 7.02%
- 20-year fixed: 6.84%
- 15-year fixed: 6.32%
- 5/1 ARM: 7.33% [1]
Mortgage rates remained in the upper 6% range, with the 30-year conventional at 6.85%, FHA at 6.55%, and jumbo at 6.84%. Higher oil prices and renewed Middle East tensions lifted inflation concerns and pushed Treasury yields higher.
Boston condos for sale: What’s the deal with mortgage rates?
In this video, we dive into why mortgage interest rates are rising again.
Boston condos for sale: What’s the deal with mortgage rates?
Mortgage rates are unchanged and still under 7%. Today’s national average on a 30-year fixed-rate mortgage is 6.27%, according to Bankrate. If you choose a 15-year fixed-rate mortgage, the average rate is 5.58%.
On December 10, the Federal Reserve lowered the federal-funds rate by a quarter of a percentage point. In response, the 10-year Treasury yield dropped, which means we’ll likely see mortgage rates fall a bit in the coming days as well.
The Fed also released new projections showing that most policymakers expect to lower rates at least once more in 2026, so mortgage rates could drop further next year—though it depends on what happens in the economy. Inflation is still above the Fed’s 2% target, but the labor market has also been showing some signs of softness. If the unemployment rate continues to inch up, mortgage rates might go down in anticipation of more Fed cuts. If labor market conditions hold steady or inflation rises, rates might remain near their current levels.
Boston condos for sale: What’s the deal with mortgage rates?
________________
Boston condos for sale: What’s the deal with mortgage rates?
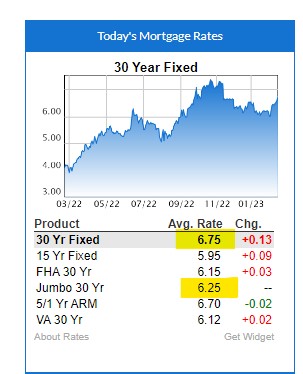
Boston condo mortgage rates are heading for 7% again, which is shocking, given it was 5.99% on Feb. 2. 2023.
Higher rates will discourage both Boston condo buyers and sellers, and make them want to wait for a “better market” some day in the future. Whether that day will come isn’t considered – all they know is that it isn’t today.
It should mean that the Boston condo market will be cleared of any casualness, and only the highly motivated buyers and sellers will be engaging. I feel Boston condo buyers will be more picky, and sellers will need to be sharp on pricing.
How sharp?
It will be different in each Boston neighborhood.
__________________________________________________________________________________________
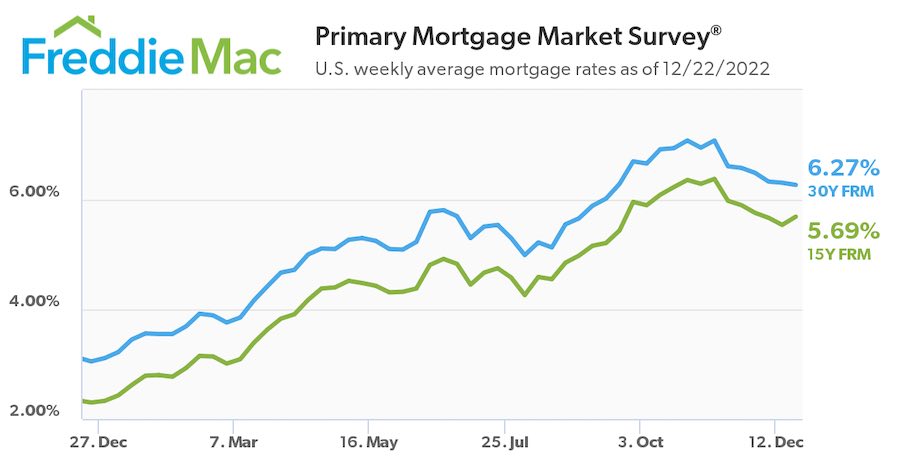
Mortgage interest rates will likely go down a little more but I don’t think we are going to see rates below 5% any time soon.
Condominium prices in the Boston metro area are not falling but rising much more slowly. This time of year, Boston condo sales are traditionally slow and I suspect this will continue through the first month of 2023.
The slightly lower interest rates make Boston condos for sale just a little more affordable. Mortgage interest rates reached a 20-year high last October.
In other news, rents have been stable as far monthly rents after going up last spring and summer.
Updated: Boston Real Estate Blog 2022/2023
______________________________________________________________
Mortgages rates have found another record low, potentially boosting a housing market that has been a bright spot for a shaky U.S. economy.
The average for a 30-year fixed loan fell to 2.88 percent, the lowest in nearly 50 years of record-keeping by Freddie Mac. It was the eighth time since the coronavirus started roiling financial markets that rates have dropped to a new low.
Boston Job Market
As of now, the Boston job market is very strong and the metro region has expanded economically and we are continuing to see an increase in population as Boston is still one of the places people are moving to for a better lifestyle. That means the region is continuing to see higher demands for Boston condos for sale. The problem is that prices are on the rise so much it’s pricing out buyers.
While we do not know exactly what the rest of 2020 will look like, this lowering mortgage rate has been a spark of optimism in our Boston housing market for both sellers and buyers. If you have been thinking about buying a Boston condo for sale in 2020, you should move rather quickly this year and take advantage of this window of opportunity. The only problem is the low amount of supplies at the moment because we are still in the COVID-19 market. If you do see some places that you like that are currently for sale, please talk to me. I have helped a lot of homebuyers in the Boston downtown condo market.
Boston Real Estate and the Bottom Line
If you have money and a job this is an ideal time to buy a Beacon Hill condo for sale or a high rise condo.

